PDF · Handwritten Notes
PGBP Adjustment Sheet by CA Amit Mahajan for CA Inter Income Tax (Sept 2026 and Jan 2027)
- Shared by
- CA NOTE HUB
- Course
- CA Inter
- Subject
- Other Stuff
- Added
- 25 Aug 2026
Part of: CA Inter
Continue reading in the Studycaller app
The full PDF — free to read, save and share in the app.
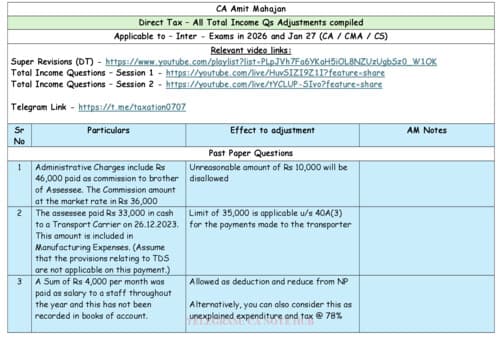
This PGBP adjustment sheet by CA Amit Mahajan collects the adjustments that keep coming up in total income questions in CA Inter Income Tax. Each adjustment is taken from past paper questions and set out in three columns: the particulars as given in the question, the effect of the adjustment on income, and a short explanatory note. The pages cover disallowance of excess payments to relatives, the cash payment limit for transporters under section 40A(3), unrecorded expenses, loss on shares, housing loan interest and principal, foreign tour expenses, fees paid to non-residents without TDS, and MSME payments under section 43B. Several items also compare the normal scheme with section 115BAC. The sheet is marked for Inter exams in 2026 and January 2027 for CA, CMA and CS students, and suits anyone practising the long computation question.
What the PGBP Adjustment Sheet Covers
The sheet is built as a table with three columns: Particulars, Effect to adjustment and AM Notes. Every row is a past paper adjustment, so you see the exact wording an examiner uses next to the treatment. Examples in the opening pages include commission of Rs 46,000 paid to the assessee's brother when the market rate is Rs 36,000, where the unreasonable Rs 10,000 is disallowed. A cash payment of Rs 33,000 to a transport carrier is checked against the Rs 35,000 limit under section 40A(3). Unrecorded staff salary is allowed and reduced from net profit, with an alternative of treating it as unexplained expenditure taxed at 78%. Other rows deal with loss on sale of shares shifted to capital gains, a housing loan with three separate effects, a Taiwan business trip with a marriage-ceremony portion, fees for technical services to a non-resident without TDS, fire insurance on a part-let building, payment to an approved scientific research association, and purchases from micro and small enterprises paid late or in cash.
Key PGBP Adjustment Points to Remember for the Exam
Several rules from these pages are worth memorising. Payments to related persons are allowed only up to the market rate; the excess is disallowed. For payments to transporters, the cash limit under section 40A(3) is Rs 35,000, not Rs 10,000. Fees for technical services paid to a non-resident without deducting tax are disallowed 100%. Common expenses such as fire insurance on a building used partly for business are allowed only for the business portion, here half of Rs 66,000. The housing loan example shows interest of Rs 2 lakh under house property, principal under section 80C and up to Rs 50,000 under section 80EE, all only under the normal scheme. Payment to an approved research association is allowed fully in the normal scheme but disallowed under section 115BAC. For MSME suppliers, payment must be made within 45 days with an agreement and 15 days without one, otherwise deduction moves to the year of payment. A later cash payment for an expense already allowed is treated as deemed income in the next year.
How to Revise with These Notes
Use the sheet after you have read the PGBP chapter in the ICAI study material, since it explains how to apply a rule rather than teaching it from scratch. Cover the Effect column, read each particular and write your own treatment, then compare it with the answer and the AM Notes. Pay close attention to rows that show an alternative view, such as the unrecorded salary and the foreign tour, because the exam may accept either assumption if it is stated clearly. When you attempt total income questions from RTPs, MTPs and past papers, keep the sheet open and tick off each adjustment type as you meet it. Mark the rows that differ between the normal scheme and section 115BAC in a separate colour, as these are easy to miss under time pressure. In the last week before the exam, a single read through the table is a quick way to recall the treatment of many small adjustments that carry marks in the computation question.
Who Should Use This CA Amit Mahajan Sheet
The sheet is labelled for Inter level exams in 2026 and January 2027 and names CA, CMA and CS students, so it suits those preparing for the September 2026 and January 2027 attempts. It is most useful for CA Inter Taxation, Paper 3, where a long total income or business income computation is common and each adjustment carries part marks. Students who have finished the PGBP chapter but lose marks on treatment of individual items will gain the most, as will those following CA Amit Mahajan's direct tax revision. The explanations are short and partly in conversational Hinglish, for example the note on the Rs 1.34 lakh cash payment to a small enterprise, which makes the reasoning easy to follow. It is a revision and practice aid, so pair it with full study material for concepts and with your own written answers for presentation.
Key topics in these notes
- Payment to relatives above market rate
- Section 40A(3) cash limit for transporters
- Unrecorded expenses and unexplained expenditure
- Loss on sale of shares in P&L
- Housing loan interest Section 80C and 80EE
- Foreign tour expenses for business
- Fees for technical services to non-resident without TDS
- Fire insurance on partly let building
- Section 35 scientific research association
- Normal scheme vs Section 115BAC
- Section 43B MSME payment within 15 or 45 days
- Deemed income on later cash payment
Explore more Taxation notes
Related notes
- GST COMPUTATION MASTER ADJUSTMENTS SHEET BY CA AMIT MAHAJAN FOR SEPTEMBER, 2026 AND JANUARY, 2027
- CA INTERMEDIATE DIRECT TAX [INCOME TAX] TOTAL INCOME ADJUSTMENTS SHEET BY CA YASH KHANDELWAL
- CA INTERMEIDATE DIRECT TAX [INCOME TAX] SARANSH | SUMMARY CHART NOTES FOR LAST MOMENT QUICK REVISION BY THE ICAI FOR SEPTEMBER, 2026 AND JAN
- CA INTERMEDIATE DIRECT TAX | INCOME TAX AMENDMENTS SHEET FOR MAY, 2026 | JUNE, 2026 | SEPTEMBER, 2026 | DECEMBER, 2026 | JANAURY, 2027 BY DA
- INCOME TAX CASE SCENARIO BASED MCQs BOOKLET BY CA YASH KHANDELWAL FOR SEPTEMBER, 2026 AND JANAURY, 2027
- CA INTERMEDIATE DIRECT TAX [INCOME TAX] PGBP ALL IMPORTANT ADJUSTMENTS SUMMARY NOTES
- Time of supply summary notes exam quick revision September 2026 and Jan 2027 exam
- CA INTERMEIDATE INDIRECT TAX [GST] SARANSH | SUMMARY CHART NOTES FOR LAST MOMENT QUICK REVISION BY THE ICAI FOR SEPTEMBER, 2026 AND JANAURY,
What to study next
Frequently asked questions
What is a PGBP adjustment sheet?
It is a table of adjustments from total income questions showing how each item affects profits and gains of business or profession. This sheet by CA Amit Mahajan lists past paper adjustments with their effect and a short note.
Which attempts is this PGBP adjustment sheet for?
The sheet is marked as applicable to Inter level exams in 2026 and January 2027 for CA, CMA and CS students.
What is the cash payment limit for transporters under section 40A(3)?
As per the sheet, the limit for payments made to a transporter is Rs 35,000, so a cash payment of Rs 33,000 to a transport carrier is within the limit.
Is fee for technical services paid to a non-resident without TDS allowed?
No. The sheet treats such payment as disallowed 100%.
How are MSME payments treated under section 43B in these notes?
Payment must be made within 45 days if there is an agreement and within 15 days if there is none; otherwise the deduction is allowed in the year of actual payment.
Does the sheet show differences between the normal scheme and section 115BAC?
Yes. For example, payment to an approved scientific research association is allowed fully under the normal scheme but disallowed under section 115BAC, and housing loan deductions apply only under the normal scheme.
How can I get the full PGBP adjustment sheet PDF?
Open it free in the Studycaller app.