PDF · Handwritten Notes
Rectification of Errors CA Foundation Handwritten Notes with Solved Examples
- Shared by
- Tanvi
- Course
- CA Foundation
- Subject
- Accounting
- Added
- 19 May 2024
Part of: CA FoundationAccountsHandwritten Notes
Most read on this topic: Rectification of error practice and previous questions
3 more notes on this topic ↓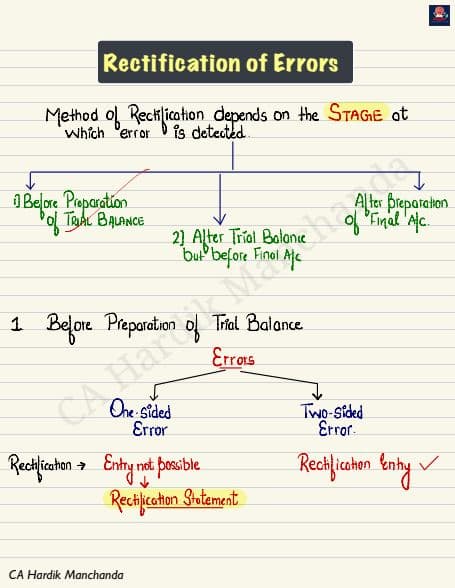
Continue reading in the Studycaller app
The full PDF — free to read, save and share in the app.
Rectification of errors is a core CA Foundation Accounting topic, and these 24-page handwritten notes explain it step by step. The notes start by showing that the method of rectification depends on the stage at which an error is found, such as before the trial balance is prepared or after the trial balance but before final accounts. They then separate one-sided errors from two-sided errors and show how each is corrected, through a rectification statement or a rectification entry. Solved questions cover undercasting of the Purchases Book, omitted depreciation postings, double posting of salary, wrong posting of the Bills Receivable Book total and errors of principle. The notes suit CA Foundation students who want a clear, exam-style way to write correcting entries and account postings for this chapter.
What these rectification of errors notes cover
The notes open with the basic rule that how an error is rectified depends on when it is detected. Errors found before the trial balance is prepared are split into one-sided and two-sided errors. For one-sided errors, no full journal entry is possible, so the correction is made by posting a narration in the affected account, for example Purchases Account debited 'To undercasting of Purchases Book Rs. 100' or Salaries Account credited 'By double posting Rs. 75'. Two-sided errors are corrected with a rectification entry, which the notes explain as reversal of the wrong entry plus the correct entry. A three-column layout of Correct Entry, Wrong Entry and Rectification Entry is used for examples such as furniture of Rs. 500 charged to Purchases Account, proprietor's drawings of Rs. 100 debited to Trade Expenses and a clerk's salary of Rs. 125 debited to his personal account. The previewed pages cover the first part of the chapter, and the remaining pages of the 24-page note continue in the full PDF.
Key points to remember for the CA Foundation exam
First, always identify the stage of detection before writing anything, because the same error is treated differently before and after the trial balance. Second, classify the error as one-sided or two-sided. A one-sided error affects only one account, such as an undercast subsidiary book total or a sale to Hari of Rs. 151 posted as Rs. 115, where only Hari's account needs a further debit of Rs. 36. Third, watch the amount in reversal cases: when the Bills Receivable Book total of Rs. 1,500 is posted to the credit side instead of the debit, the correction is Rs. 3,000, not Rs. 1,500. Fourth, for two-sided errors, write the correct entry and the wrong entry side by side, then cancel the wrong account and record the right one. Errors of principle, such as capital items charged to revenue or drawings charged to expenses, are frequent exam favourites, so practise them until the entry comes naturally.
How to revise with these notes
Start by reading the stage-wise chart at the beginning of the notes so the overall structure is clear. Then attempt each solved question yourself before looking at the handwritten solution, especially the seven-error set covering the Purchases Book, depreciation, salaries, Bills Receivable, Hari, discount to Satish and goods sold to Ram. Use the Correct Entry, Wrong Entry and Rectification Entry columns as a template for every new question you practise. After the notes, work through the rectification questions in the ICAI study material for CA Foundation Accounting, and then the relevant questions in recent RTPs, MTPs and past papers to see how the chapter is asked. Keep a short list of tricky cases, such as double posting, reversal of sides and posting the wrong amount, and revisit it a day before the exam. For chapter weightage, check the latest ICAI paper pattern rather than relying on old estimates.
Who should use these rectification of errors notes
These notes are written for CA Foundation students preparing Paper 1, Accounting, and are most useful for those who find the difference between one-sided and two-sided errors confusing. Because every example is solved in a simple, handwritten format, beginners can use them for first-time learning, while students close to the exam can use them for quick revision of entries and narrations. The examples use small round amounts, so the focus stays on the logic of correction rather than on calculation. Commerce students in Class 11 who study rectification of errors in basic accounting may also find the explanations of trial balance stage errors helpful. Students who already know the theory but lose marks on account postings for one-sided errors, or on doubling the amount in reversal cases, should give special attention to the worked solutions. The full note can be opened free in the Studycaller app.
Key topics in these notes
- Stages of rectification of errors
- Errors before preparation of trial balance
- Errors after trial balance but before final accounts
- One-sided errors
- Two-sided errors
- Rectification statement through account postings
- Rectification entry: reversal of wrong plus correct entry
- Undercasting of Purchases Book
- Wrong posting of Bills Receivable Book total
- Errors of principle: capital vs revenue
- Drawings wrongly debited to expenses
- Double posting and omission of posting
Explore more Accounting notes
- rectification of errors
- ca foundation
- accounting
- trial balance
- one-sided errors
- two-sided errors
- handwritten notes
Related notes
- CA foundation accounts journal,ledger, trial balance. Handwritten notes
- CA foundation Depreciation handwritten notes
- CA Foundation Accounts Sept 26 - Company Accounts Handwritten notes
- Summary of notes of account Rectification of error
- Accounts true or false
- Accounts theory notes
- accounts jan copy
- Handwriting notes of NPO ACCOUNTS
More notes on this topic (3)
Comments from students
Aditya · 30 May 2024
Are bhai sir ne bakki ne notes upload nahi kiye
What to study next
Frequently asked questions
What is rectification of errors in CA Foundation Accounting?
It is the process of correcting mistakes made while recording or posting transactions. These notes show that the method depends on the stage at which the error is found and whether it is one-sided or two-sided.
How is a one-sided error rectified before the trial balance?
A full journal entry is not possible, so the affected account is corrected directly with a narration, such as debiting Purchases Account 'To undercasting of Purchases Book'.
How do you rectify a two-sided error?
The notes explain that the rectification entry is the reversal of the wrong entry plus the correct entry, shown using Correct Entry, Wrong Entry and Rectification Entry columns.
Why is the Bills Receivable error of Rs. 1,500 corrected by Rs. 3,000?
The total was posted to the credit instead of the debit, so the wrong credit must be cancelled and the correct debit recorded, which doubles the amount.
What is the weightage of rectification of errors in CA Foundation?
The notes do not state a weightage. Check the latest ICAI paper pattern, RTPs, MTPs and past papers to see how often this chapter is tested.
Are these rectification of errors notes handwritten?
Yes, they are handwritten notes of 24 pages with solved examples for CA Foundation Accounting.
How can I get the full rectification of errors notes PDF?
Open it free in the Studycaller app.