PDF · Handwritten Notes
CA Foundation Accounts Notes PDF – Chapter 10 Unit 1 Partnership Accounts
- Shared by
- Sneha
- Course
- CA Foundation
- Subject
- Accounting
- Added
- 24 Mar 2024
Part of: CA FoundationAccountsHandwritten Notes
Continue reading in the Studycaller app
The full PDF — free to read, save and share in the app.
These CA Foundation Accounts notes PDF cover Chapter 10 Unit 1 (New Scheme), the opening unit of Partnership Accounts, in handwritten summary form. For students searching accounts CA Foundation revision material, the notes begin with the meaning of partnership as an agreement between two or more persons to share profits or losses, where each partner acts as principal and agent. They then explain oral and written agreements, the partnership deed and its elements, the limit on the number of partners, mutual agency as the true test of partnership, and the rules that apply when the deed is silent. The unit closes with the format of the Profit and Loss Appropriation Account and a simple diagram showing flows between the firm and a partner. Short points, arrows and a few Hindi explanations make the notes quick to revise before the exam.
What these CA Foundation Accounts notes cover
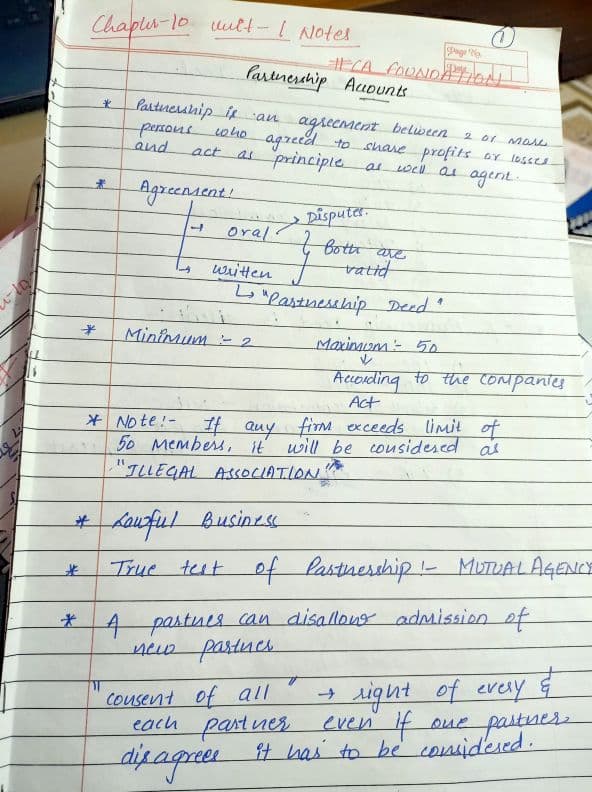
The notes open with the definition of partnership and the nature of the agreement. An agreement can be oral or written; both are valid, though oral agreements can lead to disputes, and a written agreement is called the partnership deed. The notes record a minimum of 2 partners and a maximum of 50, with a note that a firm exceeding 50 members is treated as an illegal association. Other basics listed are the need for a lawful business, mutual agency as the true test of partnership, and the consent-of-all rule under which any one partner can disallow the admission of a new partner. A separate page lists the elements of the partnership deed: name and address of the firm and partners, capital contribution, interest on capital, interest on drawings, salary or commission, interest on loan and profit sharing ratio. The third page moves to accounting of partnership firms with the Profit and Loss Appropriation Account format and a firm-partner diagram showing loan, capital, interest on capital and interest on loan.
Key points to remember for the exam
The rules when the partnership deed is silent are a frequent source of marks, and the notes put them in one list: interest on capital is nil, interest on drawings is nil, salary or commission is nil, interest on a partner's loan is 6% per annum simple interest, and profits are shared equally. Learn these five together, since practical questions often hinge on applying them correctly. In the appropriation account, the notes show the debit side as amounts the firm gives to partners, such as interest on capital, salary and commission, along with transfer to reserve and the balance profit transferred to capital or current accounts in the profit sharing ratio, labelled as divisible or distributable profit. The credit side shows what the firm receives from partners: net profit brought down, interest on drawings, and interest on current account only where the deed provides for it on a debit balance. Also remember mutual agency as the true test and the 50-partner limit.
How to revise with these notes
Use these notes as a quick recap after reading the Partnership Accounts chapter in the ICAI study material. First go through the definitions and deed elements, then close the notes and try to write the five 'deed is silent' rules from memory. Next, draw the Profit and Loss Appropriation Account format on a blank sheet and check it against the page, item by item, on both sides. Compare the placement of each item with the illustrations in the ICAI module so that your presentation matches the institute's approach. Once the format is clear, solve appropriation account questions from RTPs, MTPs and past papers, using the notes to check where interest on capital, interest on drawings, salary and reserve go. For theory MCQs, revise the points on oral versus written agreements, illegal association and consent of all. Keep the firm-partner diagram handy as a memory aid for the direction of each payment.
Who should use these accounts CA Foundation notes
These notes suit CA Foundation students preparing the Accounting paper under the new scheme, particularly those starting Chapter 10 on partnership. Because the unit builds the base for later partnership topics, students who find the appropriation account confusing can use these pages to fix the basic structure first. The handwritten, point-wise style works well for last-week revision when there is no time to reread the full module, and the occasional Hindi explanations help students who prefer bilingual notes. Commerce students in Class 11 or 12 studying partnership fundamentals may also find the definitions, deed elements and default rules useful, since the basics are similar. The notes are a summary, so treat them as a revision companion alongside the ICAI study material and practice questions rather than as a replacement for full chapter study.
Key topics in these notes
- Meaning and definition of partnership
- Oral and written partnership agreement
- Partnership deed and its elements
- Minimum and maximum number of partners
- Illegal association beyond 50 members
- Mutual agency as true test of partnership
- Consent of all for admission of new partner
- Rules when partnership deed is silent
- Interest on loan at 6% p.a. simple interest
- Profit and Loss Appropriation Account format
- Divisible or distributable profit
- Interest on capital and interest on drawings
Explore more Accounting notes
- ca foundation
- accounts
- partnership accounts
- partnership deed
- appropriation account
- chapter 10
- summary notes
Related notes
- Account CA foundation summary notes and char book
- Intermediate accounts chapter 1 handwritten notes
- Account new scheme theoretical framework June 2024
- Accounts all true or false pdf
- Account Quiz for September 26 most important
- CA foundation Accounts All chapters True/false in one place✨
- Accounts full Theory by CA Hardik manchanda Sir ✨
- Accounts theory by Hardik sir
Comments from students
Mahi❤️ · 13 May 2024
Can u share all units of ch 10
What to study next
- Newer: CA Foundation Accounting Chp-1. Theoretical Framework Unit 1: Meaning and Scope of Accounting
- Next: Redemption of preference shares all journal entries in one page.one entry is missing (write off premium in redemption) that is. securities
- All CA Foundation Accounts Handwritten Notes
- Practice next: CA Foundation Accounts MTPsRTPsPast papersMCQ practice
Frequently asked questions
Which chapter of CA Foundation Accounts do these notes cover?
They cover Chapter 10 Unit 1 (New Scheme), the introductory unit of Partnership Accounts.
Where can I get CA Foundation Accounts notes PDF for partnership?
This note is a CA Foundation Accounts notes PDF on Chapter 10 Unit 1. Open it free in the Studycaller app to read the full note.
What are the rules if the partnership deed is silent?
As listed in the notes, interest on capital, interest on drawings and salary or commission are nil, interest on a partner's loan is 6% p.a. simple interest, and profits are shared equally.
What is the maximum number of partners in a partnership firm?
The notes give a minimum of 2 and a maximum of 50 partners, and a firm exceeding 50 members is treated as an illegal association.
What is the true test of partnership?
The notes state that mutual agency is the true test of partnership.
What items appear in the Profit and Loss Appropriation Account?
The notes show interest on capital, salary or commission, reserve and profit transferred to partners on the debit side, and net profit b/d, interest on drawings and interest on current account on the credit side.
Are these accounts CA Foundation notes handwritten?
Yes, they are handwritten summary notes in short points with a few explanations in Hindi.