CA Inter doubt
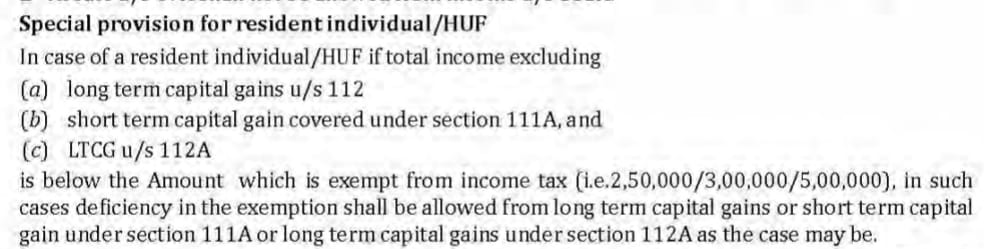
I cannot understand this provision of Chapter 1 of the Income Tax Act, 1961. Please simplify it with an example
Asked by Arya21 Jan 2025401 views
CA Inter doubt
Asked by Arya21 Jan 2025401 views
Nikhil · 21 Jan 2025
Total income (excluding capital gains) = ₹1,50,000 Long-term capital gain (Section 112A) = ₹2,00,000 Basic exemption limit (for an individual below 60 years) = ₹2,50,000 Calculation: 1. Shortfall in total income = ₹2,50,000 - ₹1,50,000 = ₹1,00,000. 2. This shortfall of ₹1,00,000 is adjusted from LTCG under Section 112A. 3. Taxable LTCG = ₹2,00,000 - ₹1,00,000 = ₹1,00,000. Tax: Tax on ₹1,00,000 LTCG (at 10%) = ₹10,000. This ensures that taxpayers with lower incomes benefit from the basic exemption limit, even when they have capital gains.
Free app · 5 lakh+ learners
Read full notes, ask doubts, follow toppers and track your study hours — free on Android and iPhone.